
Extend the application period for taxes on gasoline and diesel through the end of 2026
Deputy Prime Minister Nguyen Van Thang, on behalf of the Government, signed and issued Resolution No. 43/2026/NQ-CP on September 30, 2026, regarding the extension of the application period for preferential import duties, environmental protection taxes, and value-added tax on gasoline, diesel, raw materials for gasoline and diesel production, and aviation fuel.
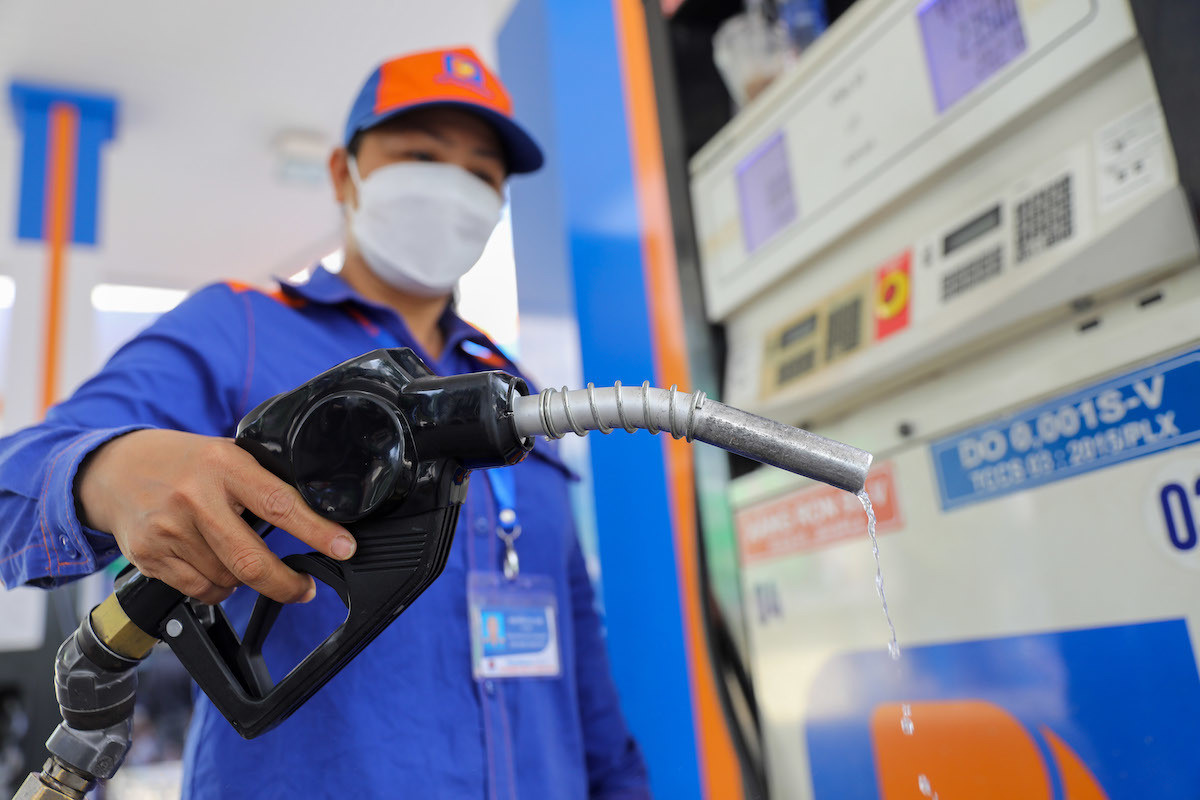
Extending the application period for preferential import taxes on gasoline, diesel, and raw materials used in the production of gasoline and diesel
Resolution No. 43/2026/NQ-CP stipulates: Extend the application period of Resolution No. 25/2026/NQ-CP dated April 30, 2026, and Decree No. 72/2026/NĐ-CP dated March 9, 2026, issued by the Government, until December 31, 2026.
Under Decree No. 72/2026/ND-CP, the preferential import tax rate is reduced from 10% to 0% for unleaded motor gasoline (HS codes 2710.12.21 – Unblended); 2710.12.22 – Blended with ethanol; 2710.12.24 – Unblended; 2710.12.25 – Blended with ethanol) and gasoline blending components such as naphtha and reformate (HS code 2710.12.80).
Preferential import duty rates have also been reduced from 7% to 0% for diesel fuel, fuel oil, aviation fuel, and kerosene.
In addition, import duties on certain petrochemical feedstocks, such as xylene, condensate, and p-xylene, have been reduced from 3% to 0%, while duties on other cyclic hydrocarbons have been reduced from 2% to 0%.
Decree No. 72/2026/NĐ-CP is effective from March 9, 2026, through April 30, 2026.
Subsequently, the Government issued Resolution No. 25/2026/NQ-CP, extending the effective period of Decree No. 72/2026/NĐ-CP until June 30, 2026.
In Resolution No. 34/2026/NQ-CP, the Government resolved to extend the effective period of Resolution No. 25/2026/NQ-CP and Decree No. 72/2026/NĐ-CP until September 30, 2026.
Extension of the application period for environmental protection tax and value-added tax on gasoline, diesel, raw materials for gasoline and diesel production, and aviation fuel
According to Resolution No. 19/2026/QH16, the environmental protection tax rate for gasoline (excluding ethanol), diesel, kerosene, mazut, and aviation fuel is VND 0 per liter.
Gasoline, diesel, kerosene, mazut, and aviation fuel are exempt from value-added tax (VAT) reporting and payment but are eligible for input VAT credits.
In addition, Resolution No. 43/2026/NQ-CP also extends the effective period of Resolution No. 19/2026/QH16 dated April 12, 2026, issued by the National Assembly, until December 31, 2026, with respect to the environmental protection tax and value-added tax specified in Articles 1 and 2 of Resolution No. 19/2026/QH16.
Resolution No. 43/2026/NQ-CP is effective from October 1, 2026, through December 31, 2026.
The excise tax on gasoline shall be implemented in accordance with the provisions of the Law on Excise Tax No. 66/2025/QH15 and the relevant implementing guidelines.
In cases where it is necessary to adjust (shorten or extend) the effective period of this Resolution to meet requirements for socio-economic development, ensure energy security, and stabilize the gasoline and petroleum market, the Ministry of Industry and Trade shall submit a proposal to the Ministry of Finance for submission to the Government for consideration and decision.
| The Ministry of Finance noted that, given the evolving global, regional, and domestic gasoline and diesel prices, the latest developments in the Middle East conflict, inflation rates, economic growth, and the extension of the application period for preferential import taxes, environmental protection taxes, and value-added tax on gasoline and diesel through the end of 2026 will help ensure energy security, stabilize the macroeconomy, control inflation, and support the recovery of production and business operations; continue to create conditions for businesses to diversify their supply sources for gasoline, diesel, and raw materials for gasoline and diesel production, reduce the risk of dependence on certain traditional import markets, and ensure supply for the domestic market under all circumstances. |