


Can children under 15 be listed as account holders on a savings account?
Reader Quang Trí (Phú Thọ) asks: My child is 10 years old this year. I would like to open a savings account at a bank for him. My question is: Can a child under 15 be the account holder of a savings account? If so, can the parents conduct transactions on the child’s behalf, and what documents are required?
Banking Times thanks you for your question. Here is our advice:
Children under 15 can have a savings account at a bank, but they cannot conduct transactions on their own; they must do so through a legal representative.
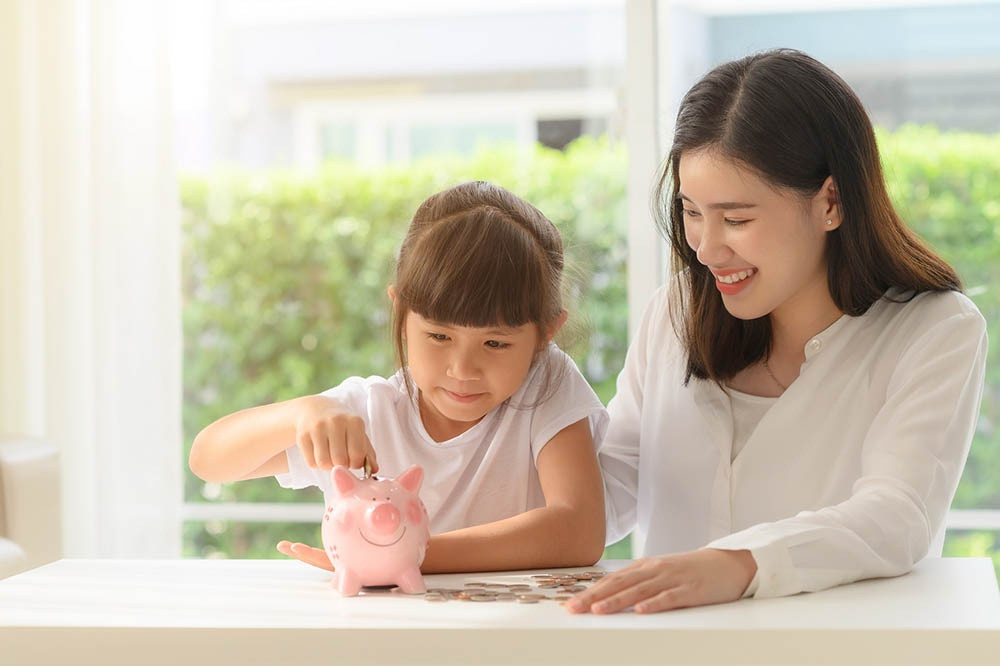
This is a common concern for many parents who wish to start saving for their children early on, particularly with money received as Lunar New Year gifts, gifts from relatives, or funds set aside by parents specifically for their children.
According to regulations on savings accounts, individuals under the age of 15 are classified as customers who cannot directly conduct savings account transactions. All transactions must be carried out through a legal representative.
Thus, while children under 15 are permitted to have savings accounts at a bank, their parents or legal guardians must handle all procedures with the bank in accordance with the regulations.
Who is the account holder?
It is important to note that the person conducting the transaction and the depositor are not necessarily the same person.
In cases where parents open a savings account for a child under 15, the account may be established in the child’s name, and the legal representative will conduct the transactions on the child’s behalf. The bank will rely on the documentation and proof of identity for both the child and the legal representative to process the procedures.
Therefore, if parents want the funds to be truly set aside for their child, they should clearly discuss with the bank when opening the savings account regarding the identification of the depositor, the legal representative’s information, and the rights and obligations related to the savings account.
At what age can a child open a savings account?
Regulations do not require a child to be a certain age to have a savings account. For children under 15 years of age, transactions are conducted through a legal representative.
This allows parents or relatives to proactively build financial savings for children from a young age. For example, if grandparents give a 10-year-old child VND 50 million, the family may consider depositing the money into a savings account for the child’s future rather than spending it immediately.
What should parents keep in mind when opening a savings account for a child?
Parents should ask the bank about the required documentation before making a transaction, including documents verifying the child’s information and proof of legal representative status.
In addition, attention should be paid to the deposit term, interest rate, interest payment method, and rules regarding early withdrawal. If this is intended to be long-term savings for the child, choosing an appropriate term will help minimize the need for early withdrawal and its impact on the interest earned.
Another point to note is that as the child grows older, the management and execution of transactions related to the savings account may change depending on the child’s age, legal capacity, and the bank’s regulations at any given time.
In summary, children under 15 years of age may open a savings account at a bank. However, at this age, children cannot conduct transactions on their own and must do so through a legal representative. Parents should discuss specific details with the bank regarding how to designate the account holder, the required documentation, and transaction rights to ensure the savings account is managed for its intended purpose.