


If you have money in the bank, don’t overlook these tips
Reader Hằng Lê (Quảng Trị) asks: I have some spare money and would like to open a savings account at a bank. Could you please tell me what depositors should keep in mind when making a deposit to protect their interests?
Banking Times would like to thank you for your question. Here is our advice:
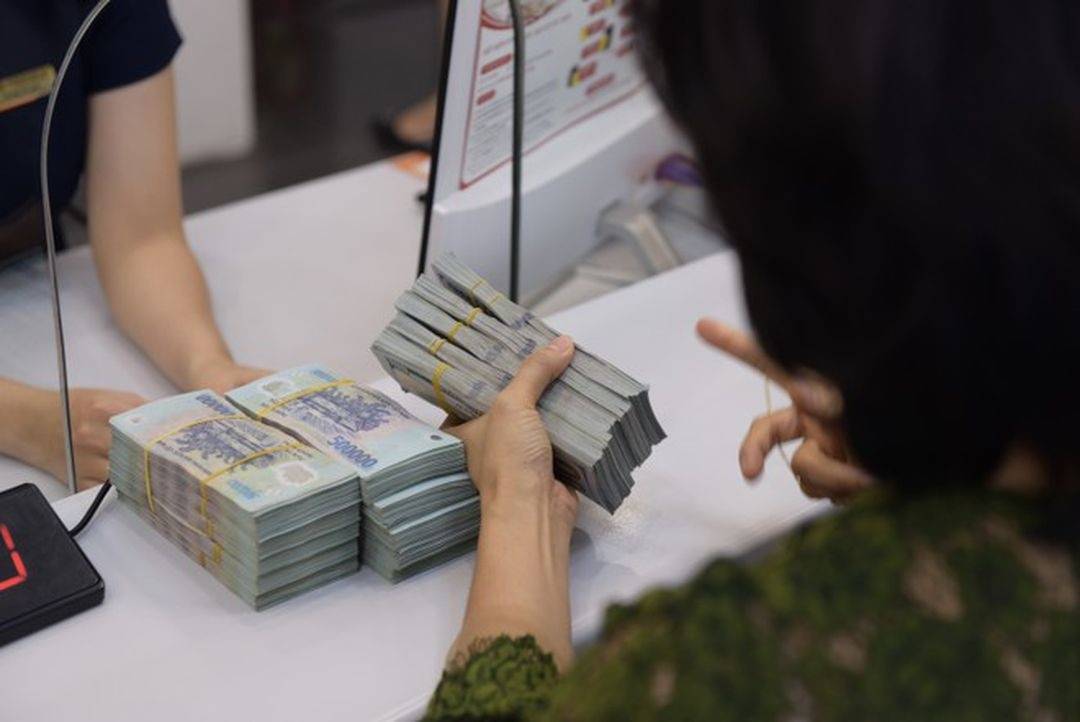
Bank deposits are one of the most popular choices for people who want to preserve their funds and earn additional income from interest. However, for a deposit to be truly effective, depositors should not focus solely on the interest rate but should also consider factors such as the term, the method of receiving interest, and the benefits associated with early withdrawal.
Don’t Just Focus on the Interest Rate
When choosing a deposit account, the interest rate is the factor that tends to attract the most attention. However, a high interest rate does not necessarily mean it’s the best option.
Depositors should also consider the deposit term, the deposit amount, how interest is calculated, and the method of interest payment. For example, if you frequently need access to funds in the short term, choosing an overly long term just because the interest rate is higher may cause inconvenience when you need to withdraw money.
Conversely, for funds not needed for an extended period, dividing them into multiple deposits with different terms can provide greater flexibility in managing cash flow.
Think Carefully Before Early Withdrawal
One point depositors should pay special attention to is withdrawing funds before the maturity date. In the event of an unexpected need for funds, customers may have to close the deposit account early, and the interest earned may be significantly lower than the interest rate for the selected term.
Therefore, before making a deposit, customers should clearly identify which funds are long-term idle funds and which may be needed in the near future.
A simple approach is to avoid putting all your idle funds into a single deposit account. Instead, consider dividing the funds into multiple accounts with different terms, tailored to your family’s financial needs.
Don’t forget the maturity date
The maturity date is an important detail depositors should keep track of. Before the deposit matures, customers can reassess their need for funds and review prevailing interest rates at that time to decide whether to renew the deposit or choose an alternative option.
In particular, customers should carefully read the deposit agreement to understand how the funds will be handled upon maturity, including whether the deposit will be automatically renewed, the method of renewal, and the applicable interest rate.
Proactively reviewing these details helps depositors avoid missing the optimal time to make decisions regarding their funds.
Be sure to read the terms carefully before making a deposit
In addition to the interest rate, customers should pay attention to the terms of the deposit product, the method of interest payment, regulations regarding early withdrawal, renewal, or any changes to information related to the deposit.
When conducting transactions, customers should also retain all relevant documents and deposit confirmation information, and proactively verify details through the bank’s official channels when necessary.
Actively divide deposit terms to manage cash flow
For those with a relatively large amount of idle funds, dividing the money into multiple deposit accounts may be a solution worth considering.
For example, instead of depositing the entire amount for a single term, depositors can allocate the funds into accounts with different maturity dates. When funds are needed, customers can use the maturing portion of the deposit rather than having to withdraw from the entire amount currently on deposit.
This approach not only helps you take a more proactive stance but also aligns with the principles of personal finance management: always keeping a portion of your funds available to meet unexpected needs.
Saving also requires a plan
Bank deposits are often chosen for their safety and to generate interest income, but the effectiveness of a deposit depends not only on the interest rate but also on how the depositor manages their cash flow.